Keep Your Client. Close the Deal. Let Me Handle the Flood.
A flood-only specialist for agents who represent one company, so your client gets the right coverage and you stay the agent they trust.
When Flood Shows Up, It Puts You in a Tough Spot
You've spent years earning that client's home, auto, and life business. Then a lender flags a flood zone, the quote comes back too high to close, or the home is worth more than federal limits will cover.
And the part nobody says out loud: if you send your client somewhere else, will they get the right advice, and will they still be your client when it's over? You shouldn't have to choose between protecting your client and protecting the relationship.
A private policy gets rejected at closing
Missing compliance language or a deductible over the lender's limit, and the closing date slips.
A flood zone shows up nobody mentioned
A refinance or HELOC triggers a new flood determination, and your client is suddenly required to buy coverage.
Your client gets cross-sold
Send them to the wrong agency, and the flood quote comes with a home and auto quote attached.
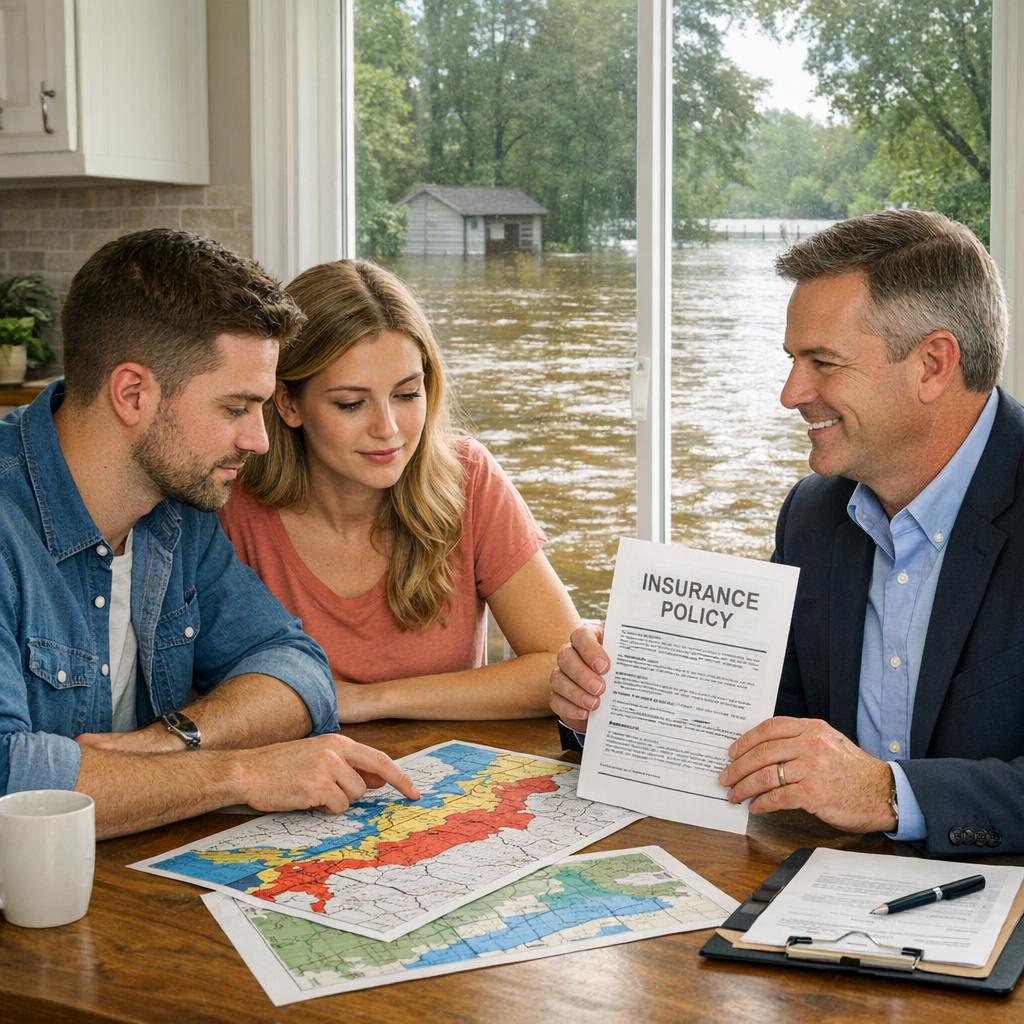
NFIP vs. Private Flood: What Every Agent Should Know
Most of your clients assume flood insurance is flood insurance. It isn't. The federal program and the private market work very differently, and the differences decide whether a closing goes smoothly and whether a claim pays.
| NFIP (federal) | Private flood | |
|---|---|---|
| Building limit (residential) | Up to $250,000 | Often higher, varies by carrier |
| Contents limit (residential) | Up to $100,000 | Often higher, varies by carrier |
| Who sets the price | FEMA, from the property's characteristics under Risk Rating 2.0 | Each carrier's own underwriting |
| Annual increases | Capped at 18% for most primary residences | Set by the carrier at renewal |
| Waiting period | 30 days, waived when tied to a loan closing | Varies by carrier, often shorter |
| Additional living expenses | Not covered | Included on many policies |
| Basement coverage | Very limited | Also limited, but a few carriers do better |
| Can the policy be dropped for claims? | No | The carrier can decline to renew |
| Transfer to a buyer | Can often be assigned to the buyer | Usually requires a new policy |
| Lender acceptance | Always accepted | Required when the policy meets the federal definition |
| When Congress lets the program lapse | New policies and many renewals stop | Unaffected |
| Surplus lines placements | Not applicable | Not backed by state guaranty funds; signed disclosure usually required |
Neither one is always better. The right answer depends on the property, the loan, and what your client can afford to lose.
The Moving Pieces Most Agents Never See
Flood looks simple from the outside. Here's what's actually moving underneath every file.
The flood zone isn't the whole story
Under Risk Rating 2.0, the NFIP rates on distance to water, elevation, rebuild cost, and more. A home outside a high-risk zone can still carry real risk, and a home inside one may qualify for a map change.
Replacement cost drives the premium
A guessed number, like dropping in a policy limit instead of a real rebuild estimate, can mean a premium that changes after closing.
Lenders have their own rules
Deductible caps, compliance language, mortgagee wording, and cancellation terms all have to line up, or the policy gets rejected at the closing table.
Leaving the NFIP has consequences
A client who moves to private and later returns can lose a discounted rate and pay the full risk premium.
Loan events trigger new determinations
Purchases, refinances, and HELOCs all pull a fresh flood determination, and zones change.
Basements and contents are where claims disappoint
Finished basements are mostly excluded, and contents coverage is often never added.
Federal authorization is always temporary
The NFIP runs on short-term extensions, so a lapse can freeze a closing.
When You Need a Specialist
You can handle a lot of flood files on your own. Bring in a specialist when any of these show up. If they sound familiar, that's where I come in.
The NFIP quote puts the closing at risk
A private option may price differently for the same property.
The home costs more than $250,000 to rebuild
That's above the NFIP's residential building limit.
The client has a finished basement
Set expectations now, not at claim time.
The flood zone looks wrong
A LOMA might remove the lender requirement.
A lender has rejected a private policy
Compliance language, deductibles, and mortgagee details need a second look.
The property is commercial
Replacement cost and property details matter even more.
Congress is near an NFIP deadline
Private flood can keep the closing on track.
Your client wants to know whether to switch
Moving off the NFIP can't always be undone.
Why Agents Trust Me With Their Clients
Now that you've told the user what may happen if they don't buy, it's time to tell them what will happen if they do. The bullets in this section should directly answer the pain points in The Stakes section. Establish your organization as an advisor and build trust.
Send Me Your ClientMore than 10,000 flood claims
I've helped clients through more than 10,000 flood claims over the last decade, including more than 2,000 during Hurricanes Helene and Debby alone. If your client ever has to file, I'll be here to help them navigate it.
More than a decade on every side of flood
I've gone back and forth with banks over flood requirements, helped push lenders toward updated ones, and worked alongside private carriers as they built their products.
Every market, not just one
NFIP, private primary, and excess flood, including coverage above the NFIP's $250,000 residential limit.
You work directly with me
Your referral doesn't go into a queue at a big company. It comes straight to me, the person who lives and breathes flood risk every day.
I've Been the Client Who Got Bad Flood Advice
I went to graduate school for a master's in emergency management, and my first day in the program was the day Hurricane Katrina made landfall. I spent two years studying what happens to families after water comes in.
Then I bought a house in a flood zone myself. The agent who helped me was a good agent, but the flood information I was given was wrong: [what coverage or requirement was misunderstood]. I didn't find out until [what happened], and I came close to losing my home.
Flood is that specialized. We know these products as well as almost anyone, not because we're smarter than everybody, but because we've been in it long enough to see almost every scenario, and to make almost every mistake ourselves, so your client doesn't have to.
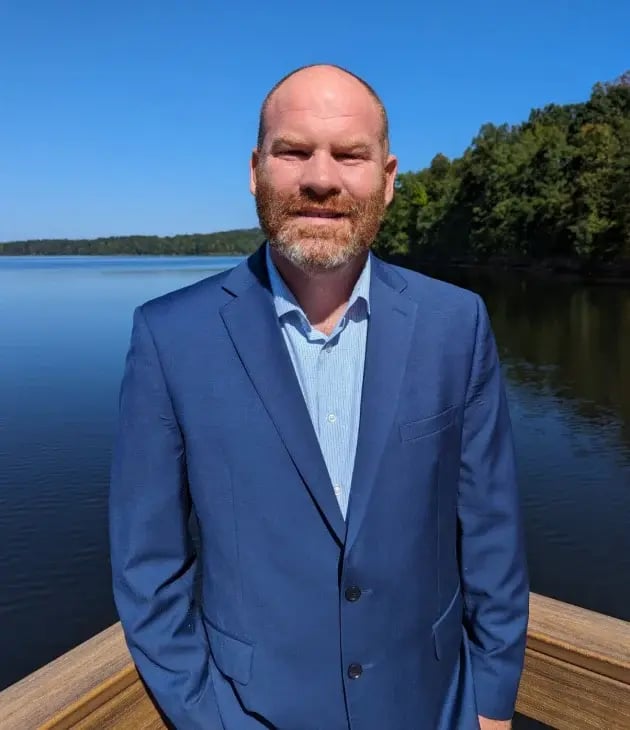
Chris Greene, Founder, The Flood Insurance Guru
Three Steps, and Your Client Stays Yours
My promise to every referring agent: nothing to cross-sell, because we don't offer anything else. Some agencies promise to flag your client's file so nobody quotes their home or auto. We don't need a flag. It can't happen, even by mistake. And you'll know when I've reached your client, when they're quoted, and when they're bound.
Send the client to me
Use the form or call 205-451-4294. A name, property address, and closing date if there is one is all I need. You can also text a referral to [1-800 number].
I handle the flood conversation
I review the flood zone, compare NFIP and private options, and explain the choice to your client in plain language.
Your client comes back to you
The flood policy is placed, the lender has what it needs, and the rest of the household stays exactly where it was.
Which Describes You?
Not ready to refer yet? Run a client's property through our Flood Risk Tool first. [Link: Flood Risk Tool]
Frequently Asked Questions
Use this section to answer questions people have about choosing a solution category. The copy for each should be only long enough to give a sufficient answer, with internal links to related blog posts for more information.
I'm a State Farm or Allstate agent. Can I refer a client to you?
Many agents who represent one company, including State Farm and Allstate agents, refer flood business to independent specialists when a client needs coverage outside what they can place. Check your own agency agreement for any referral guidelines, and I'll work within them.
Will you try to write my client's other policies?
No. We write flood insurance only.
Do you work in my state?
We place new flood coverage in every state except Louisiana and New York. Call to confirm options for your client's property.
What does my client need to get a quote?
The property address is enough to start. An elevation certificate helps, but it isn't required.
What if my client already has an NFIP policy?
I'll review it and compare private options. If staying with the NFIP is the better choice, I'll say so.
What happens if my client ever has to file a claim?
I'll be there to help them navigate it. I've helped clients through more than 10,000 flood claims over the last decade.
Stay the Go-To Agent, Even When the Question Is Flood
The closing stays on track. The realtor sees a smooth deal, and the lender gets a compliant policy on time. Your client has the right coverage and someone to call if it ever floods. And you're still the agent who knew exactly who to call.
[REFERRAL FORM PLACEHOLDER: switch this section to the Captive Agent Referral Form once it's built in HubSpot]
Prefer to talk? Call me at 205-451-4294, or text a referral anytime to [1-800 number].
The Flood Insurance Guru is an independent insurance agency and is not affiliated with, endorsed by, or sponsored by State Farm, Allstate, Alfa, Shelter, or any other insurance carrier. All trademarks are the property of their respective owners.